Fringe Benefit Tax 2025
Fringe benefits tax (FBT) is a tax paid by employers on certain benefits provided to their employees, or to their employees’ family or other associates in addition to their salary or wages. These benefits can include anything from company cars and health insurance to low-interest loans and entertainment expenses.
Fringe Benefit Tax is separate to income tax. It's calculated on the taxable value of the fringe benefit.
As an employer, you must self-assess your liability for the Fringe Benefit Tax year - 1 April to 31 March and if you have a Fringe Benefit Tax liability, you must lodge a return and pay the Fringe Benefit Tax that you owe.
What is a fringe benefit?
A fringe benefit is like a payment to an employee but in a different form to salary or wages.
There are different types of fringe benefits. Examples include:
- Allowing an employee to use a work car for private purposes
- Car parking
- Paying an employee's gym membership
- Providing entertainment by way of free tickets to concerts
- Reimbursing an expense incurred by an employee, such as school fees
- Giving an employee a discounted loan
- Giving benefits under a salary sacrifice arrangement with an employee.
The following are not fringe benefits:
- Salary and wages
- Employer contributions to complying super funds
- Shares or rights provided under approved employee share acquisition schemes
- Employment termination payments (including, for example, the gift or sale at a discount of a company car to an employee on termination)
- Benefits provided to volunteers and contractors
- Exempt benefits, such as certain benefits provided by religious institutions to their religious practitioners.
Odometer Reading
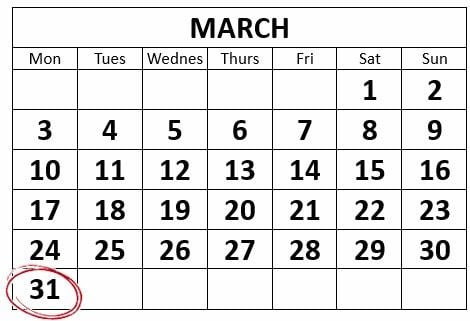
Remember to record the odometer reading of motor vehicles on the 31st March as part of your Fringe Benefit Tax obligation. This reading is one of the annual requirements of the logbook method of fringe benefits calculations.
How FBT Is Calculated
Fringe Benefit Tax is calculated based on the reportable fringe benefits amount provided and a formula set by the ATO.
Exemptions and Concessions
Several exemptions and concessions can reduce the Fringe Benefit Tax liability for employers, including:
- Benefits valued at less than $300 and provided infrequently and irregularly.
- Work-Related Items: Items such as portable electronic devices, protective clothing, and tools of the trade, which are primarily used for work.